OpenAI’s $73B Valuation and TSMC Self-Designed Chip: A New AI Vertical Integration Era
OpenAI’s move into custom silicon signals a new phase of AI integration: model developers increasingly want influence over the hardware that determines their costs, capacity, and product performance. But this is integration through partnerships, not a plan to own every layer of semiconductor manufacturing.
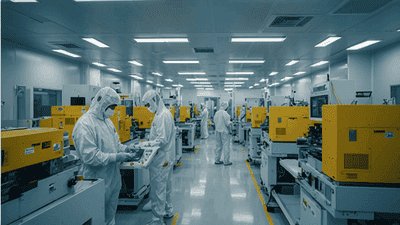
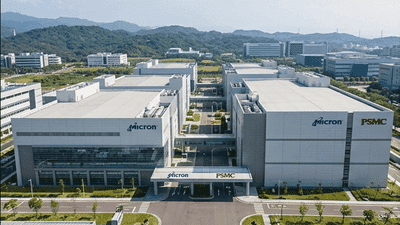
Two corrections are essential. The $73 billion valuation in the proposed title is not supported by the latest confirmed fundraising announcement. OpenAI announced $122 billion in committed capital at an $852 billion post-money valuation in March 2026. Separately, its custom inference chip, Jalapeño, was designed with Broadcom and sent to TSMC for manufacturing. TSMC is the foundry partner, not the company independently designing OpenAI’s processor.
Those distinctions sharpen the investment story. OpenAI is using capital and partnerships to gain control over computing economics while remaining dependent on specialized suppliers.
The macro implications reach well beyond AI. Interest rates affect financing, currencies reshape supply-chain costs, credit determines who carries infrastructure risk, and energy constrains the deployment of the finished chips.
The Integration Is Real, but It Is Selective
Traditional vertical integration suggests owning successive stages of production. OpenAI’s strategy is more selective.
It can influence models, software, hardware specifications, and deployment without owning a semiconductor fabrication plant.
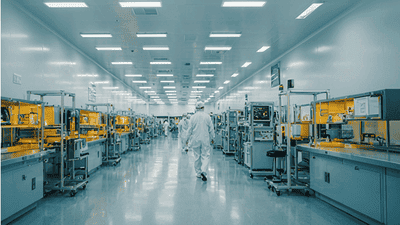
Broadcom contributes custom-chip expertise and the surrounding engineering capabilities. TSMC manufactures the design. Memory, packaging, networking, and infrastructure partners remain necessary.
The result is a coordinated production network rather than a self-contained industrial empire.
This can be economically sensible. Each participant focuses on capabilities that are expensive and difficult to reproduce.
But dependence does not disappear. It changes location. OpenAI may gain more control over accelerator design while remaining exposed to manufacturing capacity, memory availability, packaging schedules, and the financial health of its partners.
Why Inference Makes Custom Silicon Attractive
Inference is the repeated computation that produces an AI system’s responses. Its economics matter when a service handles large numbers of user requests.
A broadly programmable processor offers flexibility across workloads. A custom accelerator can target the operations and data movement that dominate a particular deployment.
That creates a potential advantage in performance, energy use, or cost—but not an automatic one.
The design must work with software, support relevant models, and operate efficiently under real traffic conditions.
Reuters reported that OpenAI unveiled Jalapeño in June 2026 and planned deployment by year-end. Broadcom’s chief executive described its performance favorably against competing platforms, but that assessment should not be mistaken for an independent benchmark across all workloads.
The commercial test is useful computing delivered at an acceptable total cost.
The Chip Is a Lever on Unit Economics
For an AI provider, revenue growth alone does not establish a sustainable business.
The cost of serving users also matters: hardware, memory, electricity, networking, facilities, software operations, and financing.
Custom silicon potentially changes that cost structure.
If a processor delivers the required workload more efficiently, it may reduce the resources needed per response or allow more useful output from a fixed infrastructure budget.
However, development expenditure and production commitments must be recovered across sufficient deployment.
A specialized design that performs well but reaches too little volume can still be financially disappointing.
The strategic question is therefore whether OpenAI has enough stable, suitable demand to justify optimizing hardware around its own workloads rather than relying exclusively on general-purpose platforms.
Valuation Is Not Infrastructure Purchasing Power
An $852 billion valuation does not mean OpenAI possesses $852 billion in cash.
It describes the equity value implied by a financing transaction. The $122 billion figure describes committed capital in that round, which is itself different from assuming every dollar was unrestricted cash immediately available on the announcement date.
Those distinctions matter when assessing infrastructure plans.
A high valuation can make equity fundraising less dilutive than it would be at a lower price. It may also signal investor confidence.
But equipment invoices are paid with cash, not valuation.
Investors therefore need to distinguish funding commitments, actual receipts, operating cash consumption, and infrastructure obligations. Otherwise, a large headline can conceal the timing mismatch between capital availability and expenditure.
Interest Rates Put a Price on the Waiting Period
Custom-chip programs commit money before dependable operating benefits arrive.
Engineering, manufacturing preparation, qualification, and deployment all require time. Higher interest rates increase the financial cost of that interval.
Debt becomes more expensive, while equity investors demand stronger returns from uncertain future cash flows.
The effect is not limited to direct borrowing. Internally funded expenditure also has an opportunity cost.
For OpenAI, the relevant calculation is whether expected improvements in computing economics justify the capital committed today.
Lower rates would ease some financing pressure, but they would not guarantee that the chip works economically or that customers generate enough revenue to support the surrounding infrastructure.
Monetary conditions influence the hurdle. Technical and commercial execution determine whether the project clears it.
Chip Financing Introduces a New Credit Layer

The hardware program is increasingly connected to large-scale financing arrangements.
In October 2026, reporting described Broadcom’s early discussions to arrange more than $50 billion in financing linked to OpenAI’s custom chips. The reported terms were still being developed, and the amount could change. This was not a completed financing transaction or a disclosed final obligation on one company’s balance sheet.
The development nevertheless illustrates a broader shift.
AI procurement can involve the chip supplier, infrastructure vehicles, private-capital providers, and the ultimate computing customer.
That structure may expand access to hardware. It also creates questions about ownership, repayment, guarantees, collateral, and residual value.
The credit risk depends on who must pay if deployment or monetization falls short.
Financing Structure Matters as Much as Financing Size
A large infrastructure funding arrangement can take several forms.
Equipment may be purchased directly, held in a separate vehicle, financed through debt, or provided under a leasing or capacity agreement.
Those approaches allocate risk differently.
Moving assets into another entity does not make their economic cost disappear. It changes where capital is committed and how payments are scheduled.
For lenders, the difficult questions concern future demand, contractual protection, hardware competitiveness, and the value of equipment if the original user cannot pay.
For suppliers, financing can support sales but may create additional exposure if commercial relationships become intertwined with customer funding.
The strongest structure aligns payment obligations with credible cash generation rather than assuming rising valuations will continually fill the gap.
The Supply Chain Remains Concentrated
Custom design reduces one form of dependence while preserving others.
A processor still needs manufacturing capacity, advanced packaging, qualified memory, testing, and supporting interconnect.
Those capabilities cannot always be substituted quickly.
This means OpenAI’s hardware control should not be equated with supply-chain independence.
The company may gain negotiating leverage and a better fit between hardware and workloads, while remaining vulnerable to constrained production resources.
The strategic benefit is strongest when custom chips diversify the available computing portfolio rather than becoming the only viable route.
Integration creates options when the wider ecosystem can support it. Without that support, a proprietary design can become another tightly coupled dependency.
Memory Costs Can Limit the Margin Benefit
Custom accelerators do not escape the economics of memory.
Reuters reported that Broadcom’s chief executive said AI-related memory demand was limiting the profit margin on the OpenAI custom chips relative to some of Broadcom’s other products.
This is an important check on the assumption that removing a branded accelerator supplier automatically creates abundant savings.
Value can shift elsewhere in the bill of materials.
If memory or packaging is scarce, those suppliers may capture part of the economic benefit. A more efficient design can still be attractive, but its returns depend on the full system cost.
For semiconductor investors, custom silicon is therefore a redistribution story as well as a growth story. The winners may include components that remain essential across competing processor architectures.
Exchange Rates Reach the Program Through Real Cash Flows
OpenAI’s infrastructure connects US financing with manufacturing and component supply across several economies.
Currency movements can alter costs and translated earnings, but the effect depends on invoicing, hedging, and payment timing.
A stronger dollar may reduce the dollar cost of some foreign-currency expenses. It does not automatically make a dollar-priced chip contract cheaper.
Manufacturers can face their own opposing exposures: export revenue may translate favorably while imported equipment becomes more expensive.
The correct analysis follows contractual cash flows rather than headquarters.
This matters because design, manufacturing, and deployment occur over different periods. A currency assumption that looks favorable during development may not hold when production payments arrive.
Energy and Infrastructure Determine Whether Chips Become Capacity
Manufacturing a custom processor is not the end of the investment.
The device needs a server, networking, cooling, electricity, and an operational facility.
Construction materials and electrical equipment affect capital costs. Energy contracts affect operating expenses. Limited availability can delay commissioning.
A power constraint can therefore postpone the return on hardware that has already been purchased.
That creates a macro linkage beyond semiconductor supply. The speed of the AI program depends partly on infrastructure systems with their own financing and construction cycles.
For investors, delivered chips and productive computing capacity should remain separate measures. Only the latter supports the intended commercial use.
Vertical Integration Changes Bargaining Power, Not Every Constraint
A credible custom-chip option can strengthen an AI provider’s negotiating position with existing hardware vendors.
It may also improve control over roadmaps and workload optimization.
But the bargaining power is conditional. The alternative must be technically effective, available at scale, and economically competitive.
Development announcements alone do not provide the same leverage as a functioning deployment.
Nor does custom silicon necessarily displace all general-purpose hardware. Different workloads and development needs can justify multiple platforms.
The likely outcome is a more diversified computing strategy, with value distributed among design partners, foundries, memory suppliers, packaging providers, and infrastructure financiers.
That is a meaningful change without requiring a complete replacement of the existing ecosystem.
The Scorecard for a Genuine New Era
The central requirement is alignment: hardware development, funding, deployment, and customer demand must arrive together.
A useful scorecard would track:
- Actual chip deployment rather than announced availability.
- Performance and cost under real workloads.
- Manufacturing, memory, and packaging readiness.
- Infrastructure utilization and operating expenses.
- Funding received relative to commitments.
- Credit obligations and risk allocation.
- Customer value relative to the capital invested.
These indicators connect the technological ambition to the financial outcome.
They also help distinguish a genuine cost advantage from a program that merely transfers expenditure into a different contractual structure.
A New Integration Model, With Old Financial Tests
OpenAI’s custom-chip program marks a serious effort to connect AI models with the hardware economics underneath them. Broadcom provides design collaboration; TSMC provides manufacturing; other suppliers provide indispensable components and infrastructure.
The confirmed valuation is $852 billion from the March round, not the title’s $73 billion. But the strategic significance does not depend on the larger number.
It depends on whether capital produces useful capacity and useful capacity produces sustainable returns.
Interest rates, currencies, credit, and commodities all influence that chain.
The new era is not complete ownership of AI production. It is deeper coordination across the stack—and a much larger financial commitment to making that coordination work.